

Loyal readers of the newsletter will know that I have couched never going “full Buffett” on gold. I make frequent references to that Bruce Greenwald quote regarding gold: it is a transition mechanism between monetary regimes, which is the thought system I still subscribe to. That being said, I own virtually none at all. I think if you’re not wealthy (like myself) or have a significant chunk of fixed rate debt (i.e. a mortgage, like me) you’re probably pretty well hedged against a debasement.
As an addendum to this, I would say that if you want the full utility of owning gold you need to own it physically, in a place only you have access to. Some of the more abstract vectors for owning gold strike me as ridiculous. Any abstraction away from the physicality of gold defeats the purpose of owning it. If there’s an EMP attack or whatever, and you own an ETF or a call spread or a blockchain-dollar-denominated claim, how could you possibly maintain ownership over this store of value without access to the internet or some centralized authority? I don’t get it. In calmer times, sure, but you’re not getting the full “value” out of the barbarous relic if you don’t own it barbarically.
Mining companies are sort of a middle-ground. They’re great for when you aren’t a survival-bullets-and-gold prepper but want to bet on a general theme of “people are going to be thinking that way for the foreseeable future”. There’s loads of operating leverage, which is what you’re playing for. Most veteran mining analysts will know what I mean by this, but the operating leverage is so severe that it actually extends to the NAV/balance sheet. A mining company’s balance sheet is less of a fixed record and more of a living, breathing organism that expands and contracts based on the spot price. This is due to the step function accounting mechanics of the cutoff grade.
The cutoff grade is the minimum amount of gold that must be present in a ton of rock for the value of that gold to cover the costs of mining, processing, and refining it. Because mining is a game of margins, the formula for the cutoff grade is heavily dependent on the gold price assumption.
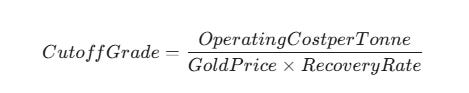
When a company performs its annual reserve audit, they must choose a conservative gold price (often lower than the current spot) to calculate what rock qualifies as a proved reserve. If they use $1,800 as their base but the gold price drops to $1,500, thousands of tons of rock that were previously Proved suddenly become Waste because they would cost more to dig up than they are worth.
This creates massive swings in NAV. Because a mine has high fixed costs (labor, machinery, debt), a 10% increase in spot can increase economically mineable reserves by 30% or more by making lower-grade ore bodies viable. Conversely, when prices dip, companies are forced to make impairment charges; the assets on their books have vanished because they are no longer profitable to touch.
Example: Imagine Mining Co. A has a deposit with a wide range of gold concentrations.
Total Mineralization: 5 million ounces.
Operating Cost: $100 per tonne of rock.
Case 1 (Gold at $2,000): The cutoff grade might be 2.0 g/t. At this price, 4 out of 5 million ounces are Proved Reserves.
Case 2 (Gold at $1,600): The cutoff grade must rise to 2.5 g/t to maintain a profit. Because the gold is spread out, only the rich parts of the vein qualify. Suddenly, Proved Reserves drop to 2 out of 5 million ounces.
In this scenario, the company hasn’t lost any gold—it’s still in the ground—but from an accounting and valuation standpoint, NAV has been cut in half. This is why veterans look for high-margin, low AISC (all-in sustaining cost) producers; they have a buffer that prevents their reserves from disappearing during a market downturn.
If you see a mining company suddenly growing its reserves during a gold bull market, check the footnotes. Are they actually finding more gold, or did they just lower their cutoff grade because the price went up? The latter is much riskier.
TL;DR: to my fellow generalists— be mindful of the accounting. Those ounces disappear when the price goes down.
i wonder if we will see this gamed out in the justification\repricing of juniors and explorers as the majors inevitably get overconfident in acquisition. or worse, as majors' c-suite have spurious compensation goals.
sounds like one of those things fewer minority shareholders will notice, as the size of momentum speculators increase.
Really sharp breakdown of cutoff grade mechanics. The 4M to 2M reserve swing without any actualgold leaving the ground is wild tbh. I've seen juniors play this game during bull runs, magically "discovering" reserves that were always there but uneconomic. The AISC buffer point separates companies that weather downturns from those whose balance sheets evaporate.